Tungsten Powder Price Faces Test of RMB 800,000 Mark - October 12, 2026
- Category: Tungsten's News
- Published on Monday, 12 October 2026 14:03
Analysis of Latest Tungsten Market from Chinatungsten Online
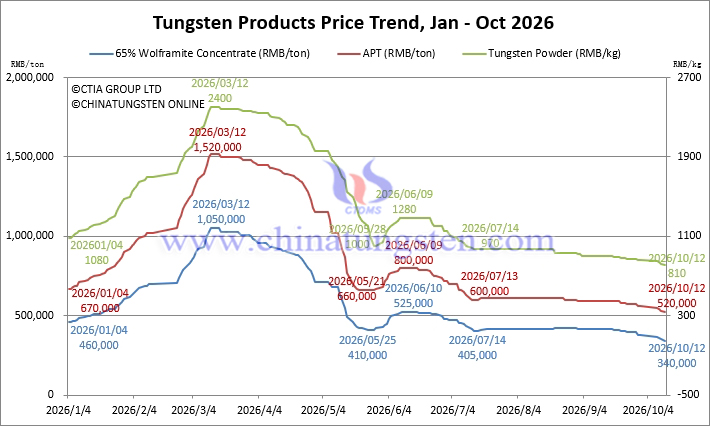
On Monday, China’s tungsten market continued to operate under pressure, with bearish sentiment dominating and localized low-price transactions further eroding market confidence. Prices of major tungsten products have cumulatively declined by more than 65% from their historical highs in March 2026 and have fallen approximately 25% from the levels at the beginning of the year, though they remain around 2.4 times the prices seen at the start of 2025.
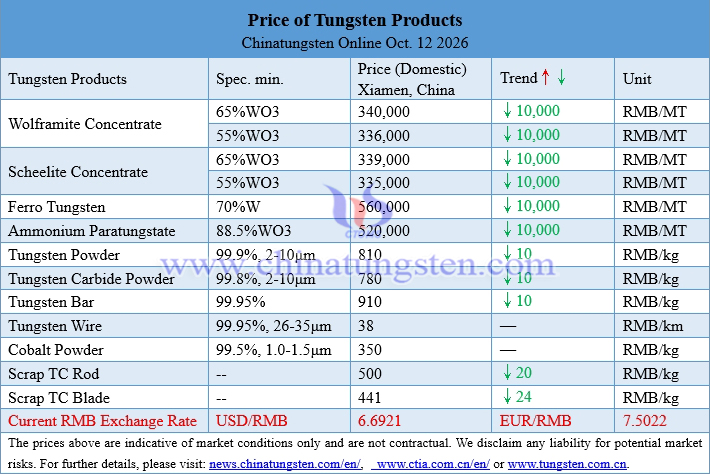
Domestic 55% tungsten concentrate is being negotiated at approximately RMB 310,000-340,000/standard ton. Ammonium paratungstate (APT) is quoted at RMB 490,000-520,000/ton. Tungsten powder is priced at around RMB 790,000-820,000/ton, while tungsten carbide powder stands at approximately RMB 750,000-780,000/ton. 70% ferrotungsten is quoted at about RMB 560,000/ton, and scrap tungsten rods at around RMB 500,000/ton.
European APT prices range from USD 2,500-2,900/mtu (equivalent to RMB 1.48-1.72 million/ton), down 14.0% from the highs and up 193.5% year-to-date. European ferrotungsten prices stand at USD 158-165/kg W (equivalent to RMB 740,000-770,000/ton), down 50.3% from the highs and up 17.5% year-to-date.
On the supply side, primary tungsten resources at the mining end remain constrained by natural endowments and policy factors, leaving limited room for domestic output growth. Imports of resources have increased noticeably, providing a certain degree of marginal supplementation to the domestic market. Operating rates in the smelting and powder segments have declined significantly since the second half of the year, with some enterprises proactively reducing or suspending production to address cost inversions and destocking pressures. However, due to the slow pace of downstream consumption, overall inventory pressure has not been fully released, and the inversion contradiction remains pronounced. In the scrap tungsten recycling segment, constrained by compliance restrictions and high holding costs, holders are generally reluctant to sell at low prices. Yet, against the backdrop of falling primary material prices, weak end-user demand, and rising market panic, scrap tungsten prices continue to come under passive downward pressure.
On the demand side, actual transactions amid the current downtrend are mostly concentrated in small-volume rigid-demand deals. Cemented carbide enterprises and their end users show limited willingness to actively build inventories, generally adopting a cautious wait-and-see approach or a back-to-back order-taking model. Speculative demand is virtually absent, with most market participants waiting for sentiment to recover or looking for opportunities to replenish stocks at lower price points.
Prices of Tungsten Products on October 12, 2026
Tungsten Price Trend from January to October 2026
- Chinatungsten Online: www.chinatungsten.com
- CTIA GROUP LTD: en.ctia.group
- Tungsten News & Price: www.ctia.com.cn
- Molybdenum News & Price: news.molybdenum.com.cn
-
Tel.: 86 592 5129696; Email:
This email address is being protected from spambots. You need JavaScript enabled to view it.