Tungsten Concentrate Prices Rise 12% This Week - October 23, 2026
- Category: Tungsten's News
- Published on Friday, 23 October 2026 17:35
Analysis of Latest Tungsten Market from Chinatungsten Online
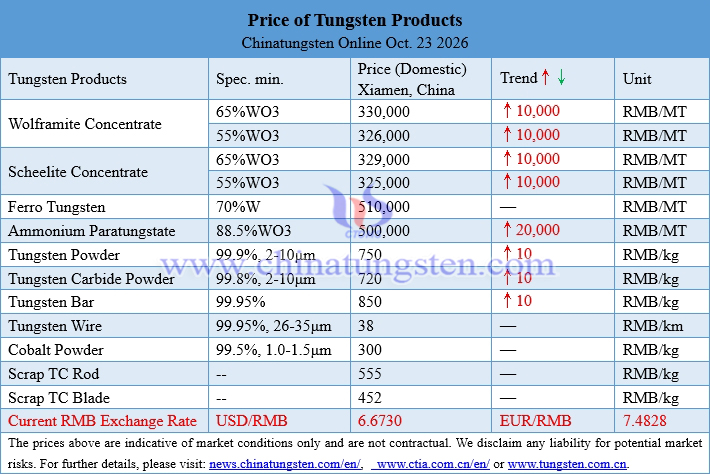
This week, the tungsten market showed a tentative recovery driven primarily by supply-side sentiment. Prices of major tungsten products rebounded noticeably from the bottom, and liquidity along the industrial chain improved somewhat. However, transactions remained dominated by small, rigid-demand orders as the market waited for further validation from the demand side.
Large tungsten producers’ concentrated purchases of ammonium paratungstate (APT) ignited firm-price sentiment on the primary raw-material side. Supply-side reluctance to sell intensified, and the steadfast guidance prices of major producers further boosted market confidence. The atmosphere in the tungsten concentrate market reversed rapidly from earlier panic selling. Concentrates grading 55% WO₃ and above found solid bottom support near RMB 300,000/standard ton, with cumulative gains of approximately 12% during the week. In the APT market, the release of orders, combined with widespread production cuts or suspensions at plants, significantly strengthened the willingness to hold and firm prices. Market psychological price levels quickly moved toward the major producers’ guidance price of RMB 500,000/ton.
The tungsten scrap market responded promptly, releasing stronger upside momentum with higher price elasticity. Taking scrap tungsten carbide rods as an example, prices rose by about 19% during the week, with volatility notably greater than that of primary materials. upward momentum was driven largely by speculative positioning among traders. Sellers, facing high holding costs and a wait-and-see-for-higher-prices mindset, showed strong reluctance to sell, making low-priced material hard to find. Actual terminal digestion remained cautious, buyers inquired actively but mostly conducted small-lot, quick-turnaround cash transactions.
When the upstream atmosphere transmitted to the powder and cemented-carbide segments, the pace slowed relatively. Driven by costs, tungsten powder prices returned to the RMB 750,000/ton level, while tungsten carbide powder prices generally stood above RMB 700,000/ton. Merchants reported that some downstream customers had gradually accepted the higher levels, yet deals remained mainly small rigid-demand orders settled on a spot basis. A wait-and-see atmosphere and cautious, needs-based operations continued to dominate the market. Confidence among cemented-carbide producers and their end users in rebuilding inventories still required further restoration. On one hand, some high-priced inventory from the previous period had not yet been fully digested, suppressing replenishment willingness; on the other hand, the market remained reserved about the stability and durability of the current rebound and was unwilling to repeat the earlier sharp rise-and-fall pattern. Overall operating strategies stayed relatively rational and cautious.
In the international market, European APT prices stood at USD 2,500-2,900/mtu (equivalent to RMB 1.476-1.713 million/ton), down 14.0% from the high and up 193.5% from the beginning of the year. European ferrotungsten prices were USD 145-160/kg W (equivalent to RMB 677,000-747,000/ton), down 53.1% from the high and up 10.9% from the beginning of the year.
Prices of Tungsten Products on October 23, 2026
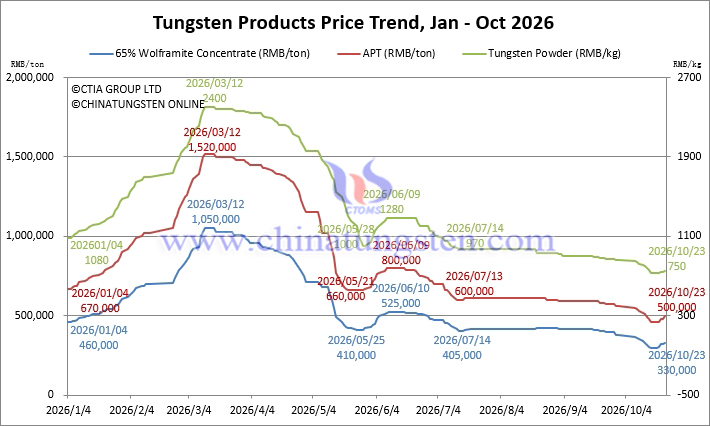
Tungsten Price Trend from January to October 2026
- Chinatungsten Online: www.chinatungsten.com
- CTIA GROUP LTD: en.ctia.group
- Tungsten News & Price: www.ctia.com.cn
- Molybdenum News & Price: news.molybdenum.com.cn
-
Tel.: 86 592 5129696; Email:
This email address is being protected from spambots. You need JavaScript enabled to view it.