Tungsten Raw Material Prices Under Pressure - September 18, 2026
- Category: Tungsten's News
- Published on Friday, 18 September 2026 13:56
Analysis of Latest Tungsten Market from Chinatungsten Online
Domestic tungsten prices this week have generally remained under pressure and weak. While upstream raw material suppliers remain keen to stabilize prices, localized instances of price-cutting to secure orders and inventory liquidation for cash have weighed on overall transaction levels. Furthermore, price concessions have failed to effectively stimulate demand; instead, they have intensified the cautious wait-and-see attitude and price-comparison behavior among downstream buyers.
Circulation along the tungsten industry chain remained relatively slow, and short-term market confidence is under pressure, with trading primarily driven by immediate needs and risk aversion. Industry participants are awaiting next week's long-term procurement quotes from major tungsten enterprises and the latest import/export data for tungsten products.
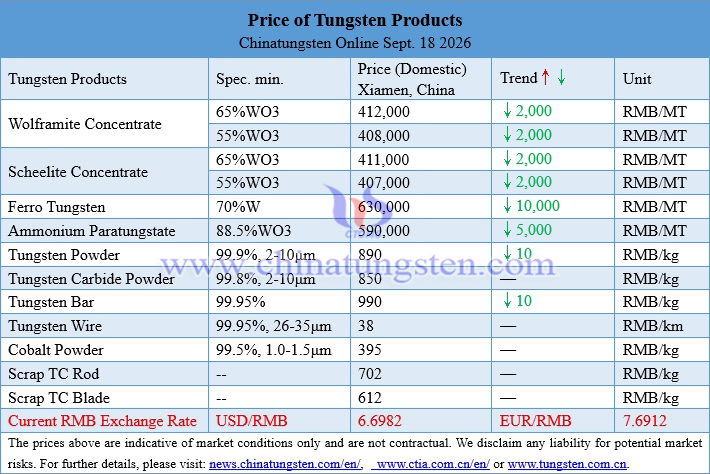
As of the time of writing, the price of 55% tungsten concentrate is consolidating in the range of RMB 400,000-410,000/ton; Ammonium Paratungstate (APT) is priced at approximately RMB 580,000-590,000/ton; tungsten powder is hovering around RMB 880,000-900,000/ton; tungsten carbide powder remains stagnant at RMB 840,000-860,000/ton; cobalt powder prices were weakly stable at RMB 395,000/ton; and the tax-inclusive price of scrap tungsten carbide rods was about RMB 700,000/ton.
European APT quotations were USD 2,900-3,000/mtu (equivalent to RMB 1.72-1.78 million/ton), unchanged week-on-week and up a cumulative 220.7% from the beginning of the year. European ferrotungsten quotations were USD 170-175/kg W (equivalent to RMB 800,000-820,000/ton), down 1.4% week-on-week and up 25.5% from the beginning of the year.
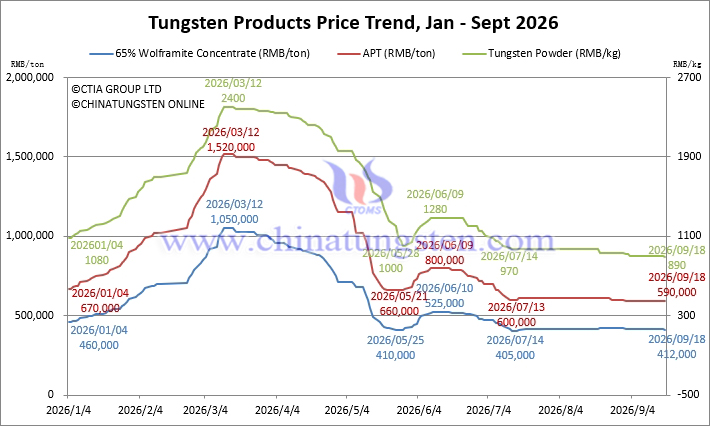
According to research by China Tungsten Online, from a medium- to long-term perspective the market remains optimistic about tungsten as a strategic resource. However, whether prices can rebound to the historical highs of RMB 1 million/ton for tungsten concentrate and RMB 2.4 million/ton for tungsten powder is subject to considerable uncertainty. After the sharp fluctuations of the past two years, participants generally believe market elasticity has increased significantly; extreme scenarios are not entirely out of the question, and both upside and downside potential exist. In the short term, however, demand pressure is more pronounced, particularly in traditional cemented carbide consumption areas such as infrastructure-related drilling and cutting tools as well as mechanical processing linked to internal-combustion vehicles. These segments have been affected by slower project progress, shrinking market share, and substitution by superhard materials, with procurement largely limited to rigid essential needs, exerting clear downward pressure on prices. On the supply side, uneven profit distribution along the industrial chain, destocking pressure, and intense internal competition have led to an interplay of price-holding and concessions.
As the Mid-Autumn Festival and National Day holidays approach, the pace of market demand recovery is falling short of expectations, suggesting that the current trend of narrow-range fluctuation and market stagnation is likely to persist. Industry participants believe that under current conditions a stable market environment would be more conducive to healthy transmission along the industrial chain. Attention should be focused on the pace of end-market consumption recovery in the fourth quarter and the extent to which suppliers uphold prices toward the end of the year.
Prices of Tungsten Products on September 18, 2026
Tungsten Price Trend from January to September 2026
- Chinatungsten Online: www.chinatungsten.com
- CTIA GROUP LTD: en.ctia.group
- Tungsten News & Price: www.ctia.com.cn
- Molybdenum News & Price: news.molybdenum.com.cn
-
Tel.: 86 592 5129696; Email:
This email address is being protected from spambots. You need JavaScript enabled to view it.