Tungsten Concentrate Prices Lowered - September 17, 2026
- Category: Tungsten's News
- Published on Thursday, 17 September 2026 16:03
Analysis of Latest Tungsten Market from Chinatungsten Online
Tungsten prices are generally under pressure, trading weakly within a narrow range. While cost factors and the nature of the resource provide some resilience, the pace of demand recovery has fallen short of expectations, leaving insufficient momentum for an upward trend. Instances of price concessions to secure orders have dampened market sentiment, leading to wider room for negotiation on tungsten products.
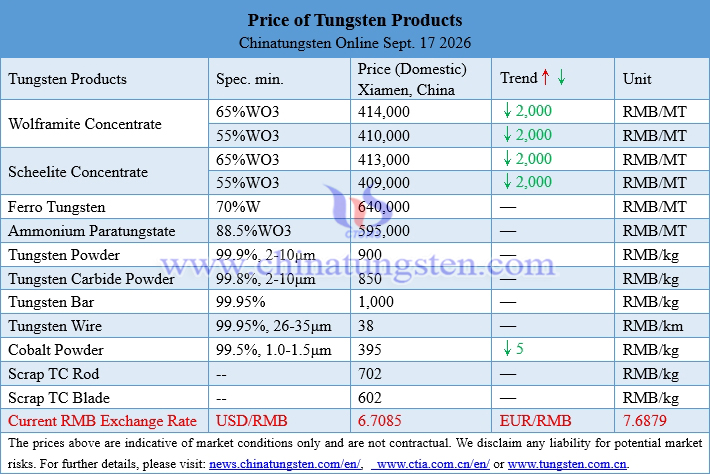
The negotiated price range for 55% tungsten concentrate has adjusted to RMB 400,000-410,000/standard ton. Supply-side constraints—stemming from limited mining capacity and trade compliance requirements—sustain a floor for market prices. However, this is countered by cautious, bearish sentiment among buyers, resulting in a stalemate in market transactions.
The price level for ammonium paratungstate (APT) hovers around RMB 590,000/ton. With limited new orders, slow resource turnover, and suppressed operating rates, the market remains under pressure while awaiting the next round of long-term procurement prices from tungsten enterprises.
Quotes for tungsten powder stand at RMB 880-910/kg, while tungsten carbide powder is quoted at RMB 840-870/kg. Instances of price concessions to attract orders are dampening market trends and trading sentiment. Manufacturers of cemented carbide and downstream products are generally placing orders based on immediate needs and negotiating cautiously, facing a combination of weak demand and capital constraints.
The tungsten scrap market remains subdued. There is divergence between buying and selling expectations, with recent pricing tilting slightly toward the buyer’s side and the transaction levels under pressure.
Cobalt prices continue their gradual downward consolidation. Recent import and recycled supply have been relatively smooth, yet consumption in cemented carbide, ternary battery materials and related sectors remains lukewarm. Purchasing enthusiasm is weak and demand-side pressure is evident. Cobalt powder prices have fallen below the RMB 400,000/ton mark.
According to data from the China Automotive Power Battery Industry Innovation Alliance, domestic power battery installations in August 2026 reached 79 GWh, up 5.9% month-on-month and 26.3% year-on-year. Of this, ternary batteries accounted for 11 GWh (14% of total installations), down 1% month-on-month but up 0.9% year-on-year; lithium iron phosphate (LFP) batteries accounted for 67.6 GWh (85.6% of total), up 7% month-on-month and 31% year-on-year. From January to August, cumulative domestic power battery installations totaled 489.1 GWh, up 17.0% year-on-year. Ternary batteries contributed 85.6 GWh (17.5% of the total, up 10.6% year-on-year), while LFP batteries contributed 402.7 GWh (82.3% of the total, up 18.3% year-on-year).
On the macro front, on 16 September 2026 the U.S. Federal Reserve unanimously decided to raise interest rates by 25 basis points, lifting the federal funds rate target range to 3.75%-4.00%. This was the first rate hike since July 2023 and formally ended the easing cycle that began in September 2024. Combined with hawkish signals suggesting possible further hikes within the year, expectations of tighter dollar liquidity have increased. The U.S. dollar index and Treasury yields strengthened, while the three major U.S. equity indexes all declined. This macroeconomic tightening has exerted pressure on precious metals (gold and silver) and bulk commodities such as copper, creating an indirect disturbance for the tungsten market. Nevertheless, tungsten price movements continue to be driven primarily by its own supply-and-demand fundamentals.
Prices of Tungsten Products on September 17, 2026
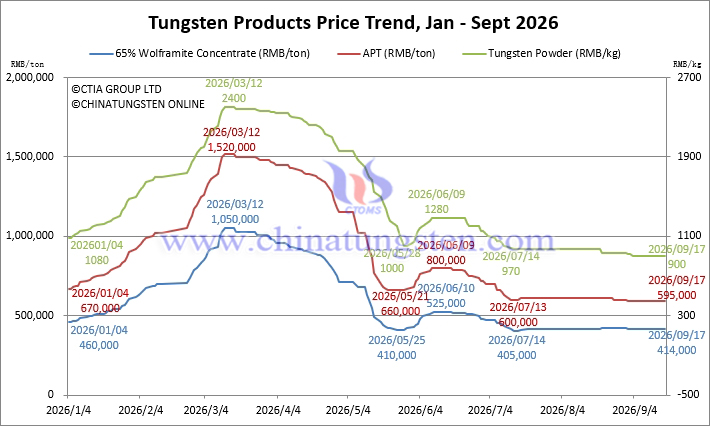
Tungsten Price Trend from January to September 2026
- Chinatungsten Online: www.chinatungsten.com
- CTIA GROUP LTD: en.ctia.group
- Tungsten News & Price: www.ctia.com.cn
- Molybdenum News & Price: news.molybdenum.com.cn
-
Tel.: 86 592 5129696; Email:
This email address is being protected from spambots. You need JavaScript enabled to view it.