Tungsten Market Supply and Demand Tug-of-War - September 10, 2026
- Category: Tungsten's News
- Published on Thursday, 10 September 2026 11:45
Analysis of Latest Tungsten Market from Chinatungsten Online
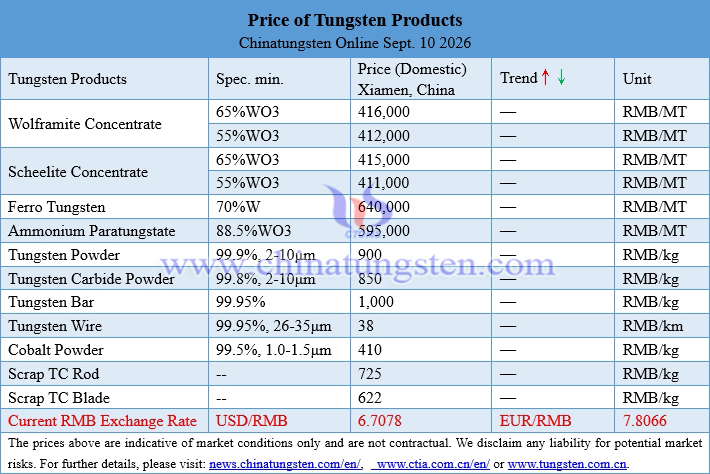
The tungsten market overall remained stable. Mainstream offers for 55% tungsten concentrate held firm above RMB 410,000/standard ton, ammonium paratungstate (APT) prices stayed close to the long-term contract procurement level of RMB 600,000/ton, and tungsten powder prices showed bottom support near RMB 900,000/ton.
Spot rigid demand saw some release recently, yet the pace of transactions remained restrained. With the supply side unwilling to sell at lower prices and overall demand limited, the market continued to exhibit a strong wait-and-see atmosphere, sticking to a cautious case-by-case negotiation approach.
Supply side
Domestic mines remained constrained by multiple factors, including total mining volume controls, safety and environmental production requirements, and declining grades of operating resources. Coupled with strict crackdowns on illegal mining and undocumented (non-invoiced) material, both capacity and circulating volumes of tungsten concentrate were effectively capped. In addition, driven by the strategic value of the resource and the need to protect corporate margins, miners maintained a firm price-holding stance, limiting the outflow of low-priced material. However, rising import volumes and a higher share of scrap tungsten recycling have eased raw-material tightness to some extent. Combined with sluggish demand since the second quarter, this has resulted in a relatively loose supply-demand balance. Recently, smelters facing compressed margins proactively cut or suspended production to adjust output and inventories. Overseas, while the development of new mines and capacity expansion are underway, factors such as construction timelines, capital constraints, and geopolitical issues hinder significant short-term output growth, necessitating continued monitoring of potential future supply increases.
Demand side
In the cemented carbide cutting-tool sector—the mainstay of tungsten consumption—terminal demand momentum remained relatively weak amid a slow macroeconomic recovery and manufacturing orders that fell short of expectations. More critically, the sharp volatility in raw-material prices earlier significantly dented downstream restocking confidence. Most enterprises have shifted to a sales-driven production model with only rigid procurement, and willingness to rebuild inventories remains low. As a result, inventory destocking at the intermediate smelting and powder stages has progressed slowly. The recent relative stability in raw-material prices has somewhat restored willingness among rigid buyers to enter the market, and participants continue to monitor whether the traditional “Golden September–Silver October” peak season will materialize. Emerging applications such as PCB drill bits, tungsten hexafluoride (WF₆), and tungsten-based high-temperature alloys possess longer-term growth potential, but their current volumes exert only limited marginal impact on overall demand.
Prices of Tungsten Products on September 10, 2026
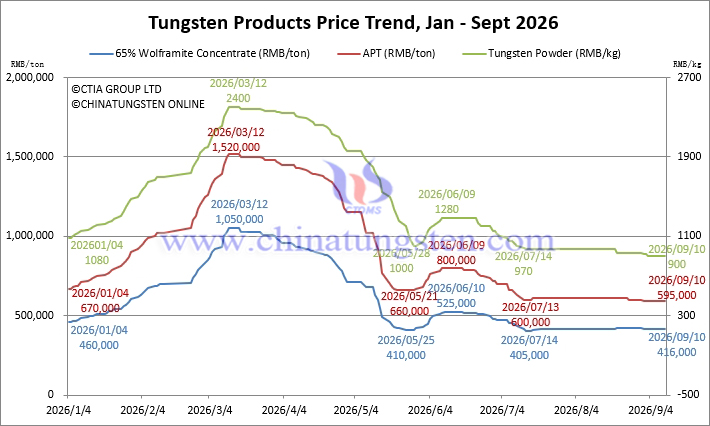
Tungsten Price Trend from January to September 2026
- Chinatungsten Online: www.chinatungsten.com
- CTIA GROUP LTD: en.ctia.group
- Tungsten News & Price: www.ctia.com.cn
- Molybdenum News & Price: news.molybdenum.com.cn
-
Tel.: 86 592 5129696; Email:
This email address is being protected from spambots. You need JavaScript enabled to view it.