Tungsten Prices Edge Down at the Start of September
- Category: Tungsten's News
- Published on Tuesday, 01 September 2026 14:09
Analysis of Latest Tungsten Market from Chinatungsten Online
As September began, tungsten concentrate prices saw a modest pullback from the RMB 420,000/standard ton level.
Industry sources note that this adjustment is more of a technical correction after earlier high quotes failed to materialize in actual transactions, rather than a substantive weakening of market conditions. Producer willingness to support prices remains firm. Nevertheless, the downward move has sparked concern among some market participants, who question whether the traditional “Golden September” peak season will materialize as expected.
According to research by China Tungsten Online, while market participants often hold seasonal expectations, the fundamental drivers of tungsten prices remain supply-demand dynamics, policy measures, and cost support. Seasonal factors act primarily as catalysts for market sentiment and short-term trading rhythms, rather than as the decisive force determining price direction. Consequently, the actual delivery of the so-called “Golden September and Silver October” still needs to be verified against underlying fundamentals.
Looking at current market performance, downstream procurement remains largely needs-based, with limited willingness to build inventories proactively. Most end-users are purchasing flexibly according to actual orders and, drawing on experience from the start of the year, are reluctant to lock in inventory early in order to manage risk. Overall transaction pace is slow and trading atmosphere relatively subdued. On the raw-material side, there is some pressure to digest inventories. Since March, stocks have gradually accumulated to relatively high levels amid soft demand; the temporary drawdown seen at the end of May proved limited in duration, and overall inventory pressure has not been effectively relieved. Combined with squeezed profit margins, smelters have reduced operating rates and shown stronger willingness to adjust supply.
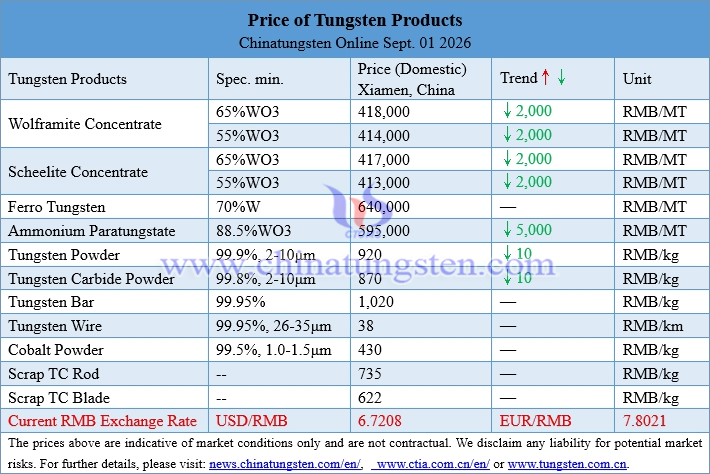
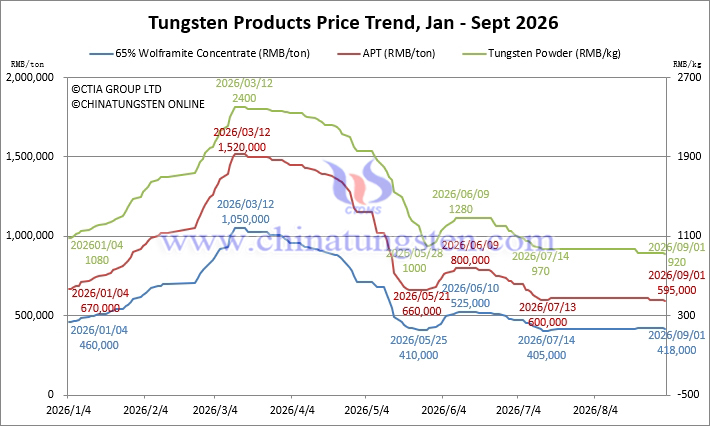
As of the time of writing, ammonium paratungstate (APT) stood at RMB 595,000/ton, down 11.2% from the beginning of the year; tungsten powder at RMB 920/kg, down 14.8%; tungsten carbide powder at RMB 870/kg, down 16.4%; and 70% ferro-tungsten at RMB 640,000/ton, down 1.5%. Scrap tungsten rod prices were at RMB 735/kg, up 8.3% year-to-date.
China Tungsten Online believes the recent modest decline in tungsten prices reflects the combined effects of supply-demand mismatch and cautious market sentiment. In the near term, prices are likely to remain in a stable-to-weak range with sideways oscillation. Upside potential is constrained by the pace of downstream demand recovery, while downside room is relatively limited owing to active supply-side adjustments and cost support; expectations of either a sharp rally or a deep correction remain low. It is still premature to declare the “Golden September” a washout. Attention should be paid to the actual release of demand from end-use sectors, long-term contract quotations and procurement strategies of major tungsten producers, and marginal changes in the broader macro-political and economic environment. The interplay of these factors will determine the quality of the September market. Until then, the market is likely to remain dominated by wait-and-see positioning and tactical maneuvering, with a clear directional trend still requiring patience.
Prices of Tungsten Products on September 1, 2026
Tungsten Price Trend from January to September 2026
- Chinatungsten Online: www.chinatungsten.com
- CTIA GROUP LTD: en.ctia.group
- Tungsten News & Price: www.ctia.com.cn
- Molybdenum News & Price: news.molybdenum.com.cn
-
Tel.: 86 592 5129696; Email:
This email address is being protected from spambots. You need JavaScript enabled to view it.